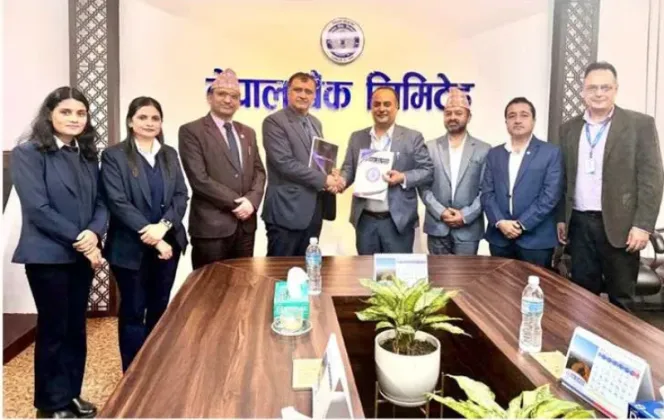
Nepal Bank Limited has partnered with fintech company Fintara Solutions to offer its credit card customers an installment facility with zero percent down payment, under an agreement announced in Kathmandu. Through the partnership, Nepal Bank cardholders can purchase goods and services via OneBNPL, the Buy Now Pay Later platform operated by Fintara Solutions, and repay the amount in monthly installments ranging from 3 to 18 months, without paying anything upfront. The arrangement, reported by RatoPati, adds a flexible repayment option to the bank's credit card offering and links the lender's card base with a dedicated digital BNPL platform.
It is worth noting that the "zero percent" figure refers to the down payment, not to the interest charged on the installments. In other words, cardholders are not required to put down an initial lump sum when making a purchase, with the repayment then spread across a tenure of their choosing.
How the Zero Down Payment Installment Facility Works
The facility is built around Nepal Bank's existing credit card products. Cardholders who shop through OneBNPL can convert their purchases into installments, selecting a repayment period of anywhere between 3 and 18 months. Because the down payment requirement is zero, the customer does not need to pay a portion of the purchase price at the point of sale, which is often a condition in conventional installment schemes.
Key Features at a Glance
- Zero percent down payment: Customers pay nothing upfront when purchasing goods and services through the platform.
- Flexible tenure: Repayment periods range from a minimum of 3 months to a maximum of 18 months.
- Dedicated platform: Transactions are routed through OneBNPL, the Buy Now Pay Later service operated by Fintara Solutions.
- Eligibility: The facility is available to Nepal Bank Limited credit card users.
The zero down payment element is the distinguishing feature of the scheme. Installment purchases in the market typically require customers to cover part of the cost at the time of buying, and removing that barrier can make larger purchases more accessible for households managing monthly budgets. By spreading payments over as long as 18 months, the facility allows cardholders to match repayment with their income cycles rather than absorbing the full cost in a single billing period.
A Commercial Bank Joins Forces with a BNPL Fintech
Fintara Solutions operates OneBNPL, a Buy Now Pay Later platform, a model of consumer credit in which customers acquire a product or service immediately and pay for it over time in scheduled installments. BNPL services have become an increasingly familiar feature of digital commerce, sitting at the intersection of payments, lending and online retail.
The agreement announced in Kathmandu connects two complementary sides of that ecosystem. Nepal Bank brings its credit card customer base and lending infrastructure, while Fintara Solutions contributes the OneBNPL platform through which purchases and installment plans are processed. Rather than building a BNPL product of its own from scratch, the bank is plugging into an established fintech platform, while the fintech in turn gains access to the customers of one of the country's commercial banks.
Partnerships of this kind have become a common route for financial institutions looking to modernize their retail offerings. For the bank, the collaboration enhances the value of an existing product, the credit card, without the cost of developing new technology in-house. For the fintech, alignment with an established lender provides reach and credibility that a standalone platform would find harder to achieve. The cardholder, in principle, benefits from both: the spending power of a bank-issued credit card combined with the installment convenience of a BNPL service.
What the Facility Means for Cardholders
For Nepal Bank's credit card customers, the immediate appeal is cash-flow flexibility. A purchase that might otherwise require a large one-time outlay can instead be broken into smaller monthly payments, and the absence of a down payment means the customer's own funds are not touched at the moment of purchase. The range of goods and services covered will depend on the merchants and service providers available through the OneBNPL network.
The 3-to-18-month tenure also gives customers room to size the facility to their needs, with shorter plans for smaller purchases and longer ones for bigger-ticket items. As with any credit product, however, customers would do well to review the applicable terms, charges and conditions before transacting, so that the total cost of an installment plan is clear alongside the convenience it offers.
With the announcement made in Kathmandu, the partnership now stands as one of the more concrete examples of a Nepali bank and a fintech firm combining forces around consumer credit. For Nepal Bank, it is a way to sharpen the appeal of its credit cards; for Fintara Solutions and OneBNPL, it is a route into the customer base of an established lender; and for cardholders, it is a new option to buy now, pay later, and pay nothing down.